U.S. Midterm Elections Put Fiscal Policy and Market Risk in Focus
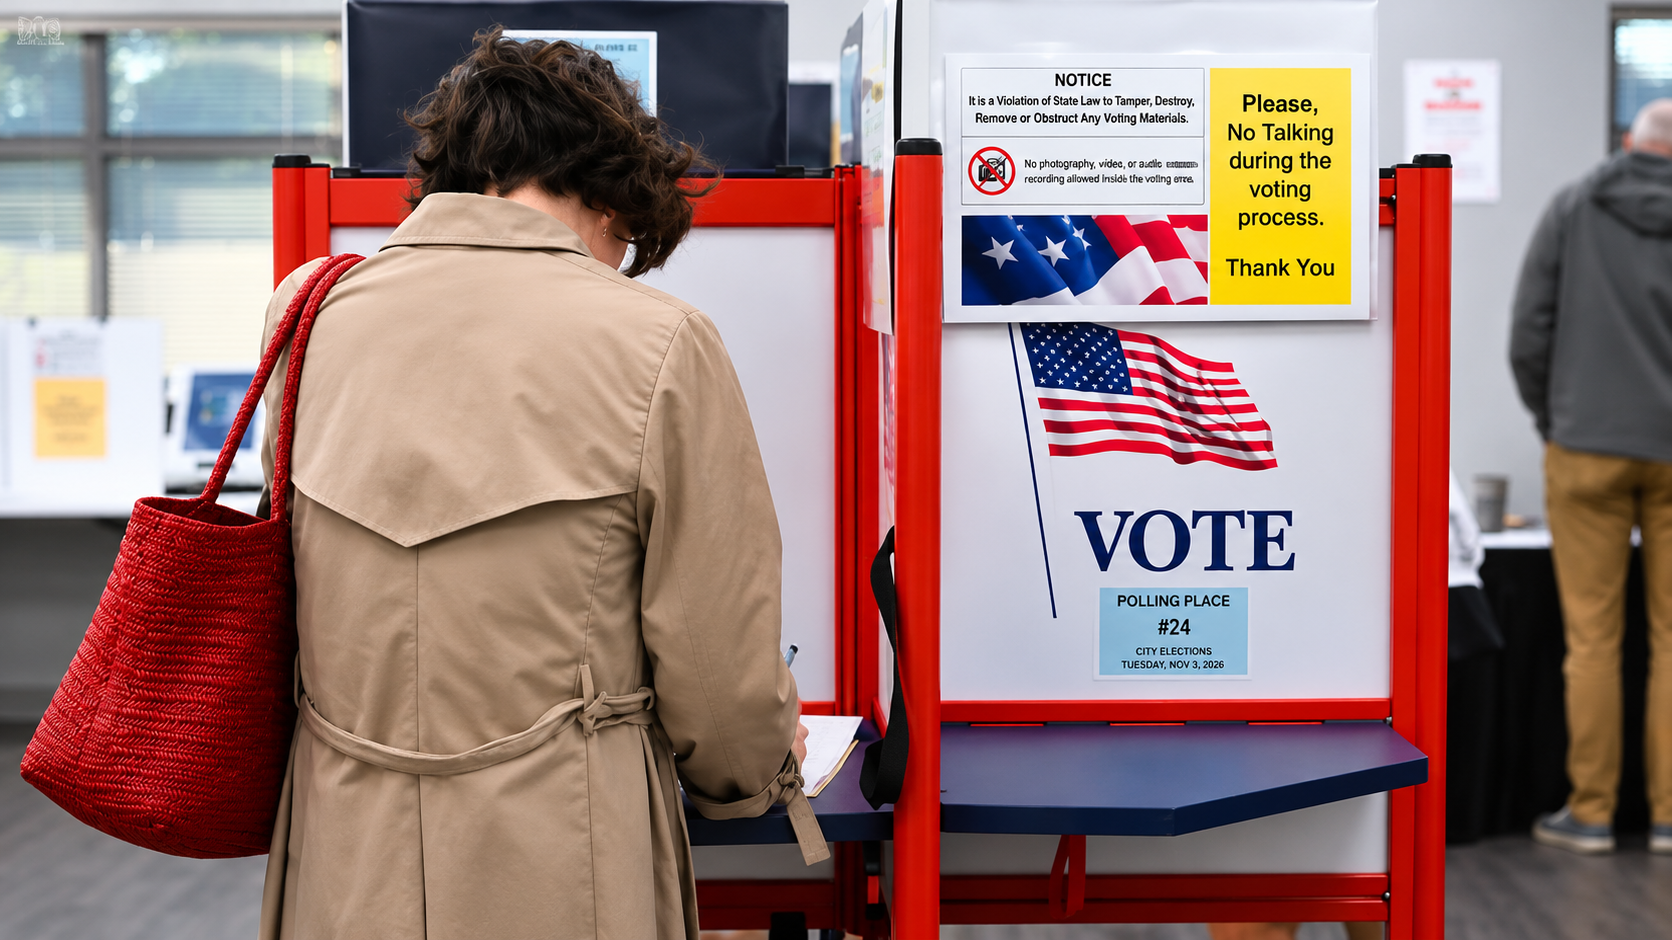
U.S. voters are casting ballots in the November 3, 2026, midterm elections, with control of Congress at stake and financial markets assessing how the next legislative balance could influence fiscal negotiations, Treasury borrowing and corporate regulation.
The vote comes at a sensitive point for U.S. assets. Government bond yields remain elevated, while technology stocks have faced renewed scrutiny over the scale and financial returns of artificial intelligence infrastructure spending. Against that backdrop, changes in congressional control could alter expectations for federal spending and oversight without necessarily determining the direction of equity or bond markets.
The central question for investors is not simply which party controls Congress, but how the resulting legislative balance affects the timing, scope and credibility of economic policy.
Fiscal Policy and the Balance of Legislative Power
President Donald Trump’s Republican Party enters the election controlling both chambers of Congress. The results will determine whether that arrangement continues or whether legislative authority becomes divided between the parties.
The economic implications depend on the composition of both chambers, the size of any governing majorities and the administration’s ability to negotiate legislation.
Continued Republican control would preserve a more favorable legislative environment for the administration’s priorities, although internal disagreements and Senate procedural requirements could still constrain major initiatives.
Divided control could increase the need for compromise on federal appropriations, tax measures and other legislation. It could also strengthen congressional oversight while making fiscal agreements more difficult to negotiate.
Democratic control of both chambers would expand oversight authority and the ability to set the congressional agenda, although presidential veto powers would continue to limit legislation that lacks sufficient bipartisan support.
These institutional differences matter for markets because they influence the probability, timing and structure of future fiscal decisions.
A divided Congress may constrain new spending initiatives, but that does not automatically translate into lower deficits. Existing statutory obligations, economic conditions, interest costs and negotiated policy changes remain important determinants of federal borrowing.
Similarly, legislative gridlock does not necessarily imply a favorable outcome for government bonds. Prolonged disputes over funding or borrowing authority can introduce uncertainty even when the scope for new legislation is limited.
Treasury Markets and Fiscal Negotiations
The election places renewed attention on the relationship between fiscal policy and U.S. government financing.
Treasury yields reflect multiple forces, including expected Federal Reserve policy, inflation, economic growth, the supply of government securities and the compensation investors require for holding longer-term debt.
Congressional control can influence some of those expectations, particularly through decisions affecting federal revenues, expenditures and borrowing requirements.
The distinction between the debt ceiling and the federal deficit is essential.
The statutory debt limit constrains the Treasury’s authority to borrow to meet federal obligations. It does not, by itself, authorize new spending or determine the size of the deficit.
A dispute over the borrowing limit can therefore create financing and payment uncertainty without reducing the government’s underlying commitments.
UBS has identified potential debt-ceiling negotiations in 2027 as one area in which a change in congressional control could generate volatility. That is a forward-looking assessment, not a confirmed funding disruption.
For bond investors, the consequences of the election will depend on whether subsequent fiscal negotiations materially change expected Treasury issuance, inflation risks or the premium demanded for longer maturities.
There is no automatic relationship between a particular congressional outcome and lower or higher yields.
Corporate Oversight and AI Infrastructure
The elections also intersect with one of the most consequential developments in U.S. equity markets: the expansion of artificial intelligence infrastructure.
Large-scale investment in computing capacity, networking equipment and data centers has supported demand across semiconductor and technology supply chains. It has also raised questions about capital intensity, electricity requirements and the financial returns associated with continued expansion.
Changes in congressional leadership could affect the degree of federal scrutiny applied to technology companies and the infrastructure supporting AI development.
Congressional committees can conduct investigations, request information and hold hearings. Those powers can influence regulatory uncertainty and corporate expectations even without new legislation.
However, congressional oversight should not be confused with enacted restrictions on AI development or data-center construction.
A material change in operating costs, project timelines or expected cash flows would depend on the substance of subsequent policy decisions and the authority of the institutions implementing them.
State and local governments also retain significant influence over permitting, land use and infrastructure development.
That division of authority limits the extent to which a congressional election alone can determine the trajectory of AI-related capital expenditure.
For equity markets, the relevant distinction is between heightened political scrutiny and policy measures capable of changing business economics.
Options Markets Price a Contained Immediate Move
Despite the potential policy implications, equity derivatives markets are not pricing an unusually large immediate reaction to the election.
According to ORATS data reported by Reuters on November 3, S&P 500 index options imply a move of approximately 0.8% in either direction for Wednesday, November 4, compared with an average implied daily move of approximately 0.6% over the preceding month.
The figures represent expected movement embedded in options prices, not a forecast of whether the index will rise or fall. They also do not establish a maximum possible market move.
The comparison suggests that investors anticipate somewhat greater near-term volatility around the election, without pricing an exceptionally large single-session adjustment.
That distinction is consistent with the nature of the event.
Election results can clarify the composition of Congress relatively quickly, while the economic consequences of that composition emerge through negotiations, legislative decisions and regulatory developments over subsequent months.
An immediate reduction in political uncertainty therefore would not necessarily resolve questions about fiscal policy, government borrowing or corporate regulation.
Other influences, including inflation, monetary policy, earnings and geopolitical developments, will continue to shape asset prices.
Market Perspectives: From Election Results to Financial Consequences
The November 3 midterm elections will establish the congressional balance within which U.S. fiscal and regulatory policy is negotiated over the next two years.
For financial markets, the implications extend beyond the initial election-night response.
Changes in legislative control could influence federal spending negotiations, the handling of future debt-limit disputes and the intensity of oversight across economically important industries.
Yet the relationship between congressional control and market performance is neither immediate nor predetermined.
For Treasury securities, the critical transmission mechanism runs through expected borrowing requirements, inflation, monetary policy and the compensation investors demand for holding government debt.
For equities, the relevant considerations are whether subsequent policy changes affect corporate earnings, capital expenditure, financing conditions or regulatory costs.
For AI-related companies, increased oversight may create uncertainty, but the financial impact will depend on whether that scrutiny produces economically consequential measures.
The options market’s relatively contained implied move reinforces the distinction between an electoral event and the longer process of policy implementation.
The election determines who will negotiate and oversee federal policy. The decisions that follow will determine whether the outcome materially changes the economic assumptions embedded in U.S. asset prices.
Important Information
This material was prepared by Wavelength Financial Content, an independent third-party content provider, and is published with the authorization of Quassar Capital, L.P. ("Quassar Capital"). Opinions expressed are as of the date of publication and are subject to change without notice. They do not necessarily reflect the views of Quassar Capital or its affiliates.
This material is provided for informational purposes only. It is not investment, legal, or tax advice, a recommendation to take any action or make any investment decision, or an offer to sell or a solicitation of an offer to purchase any security, financial product, or interest in an investment vehicle. Forward-looking statements, forecasts, and estimates are illustrative, subject to risks and uncertainties, and may not be realized. Past performance is not indicative of future results.
Information has been obtained from sources believed to be reliable but has not been independently verified, and no representation or warranty is made as to its accuracy or completeness. References to third-party companies, products, or trademarks are for identification only and do not imply sponsorship, affiliation, or endorsement. See the Disclosures and Terms of Use pages on this website for additional information.
© 2026 Quassar Capital, L.P. All rights reserved. Reproduction or distribution of this material, in whole or in part, is prohibited without the prior written consent of Quassar Capital.