Indonesian Stocks Extend Historic Rout as MSCI Downgrade Risk Threatens Global Capital Flows
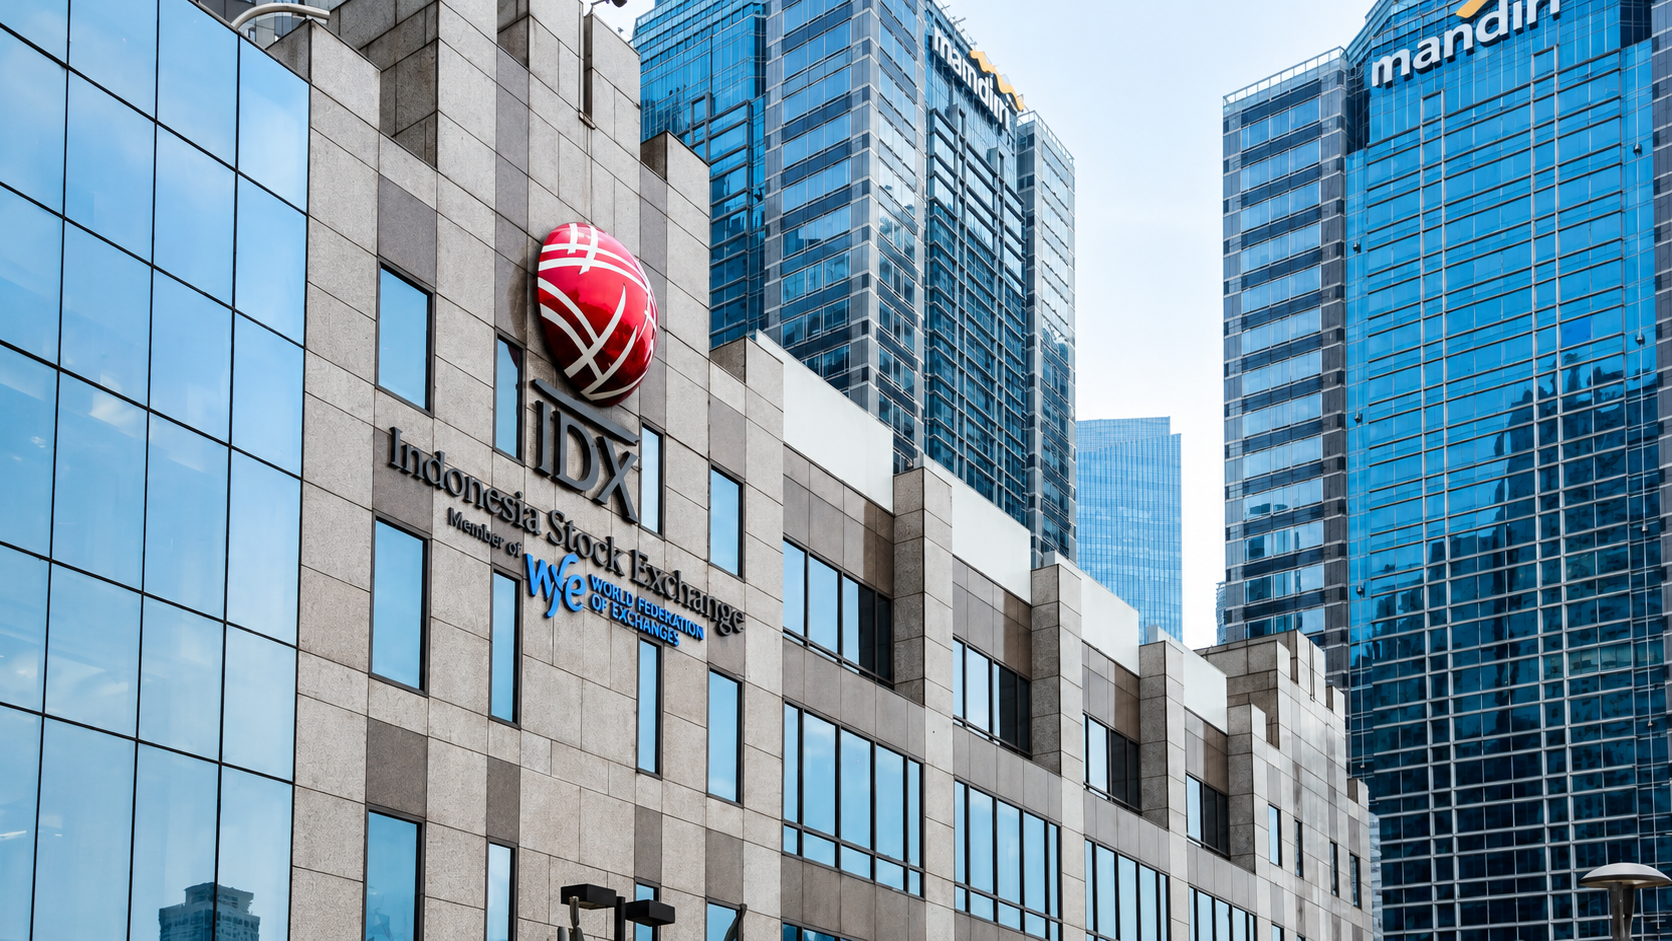
Indonesian equities extended a historic selloff on October 19, 2026, as investors reassessed the country’s position in global capital markets following MSCI’s proposal to remove Indonesia from its emerging-market classification.
Jakarta’s benchmark stock index closed 3.6% lower on Monday after plunging 11.6% on Friday, October 16. The compounded decline across the two sessions was approximately 14.8%, exceeding any comparable two-day selloff recorded during the 1998 Asian financial crisis, according to Reuters.
The index also reached its lowest level in six years during Monday’s trading.
The immediate source of pressure was MSCI’s October 15 announcement that it had launched a consultation on reclassifying Indonesia from Emerging Market to Standalone Market status.
The proposal represents a potentially consequential change in the institutional framework governing international investment in Indonesian equities.
Although no final reclassification decision has been made, the prospect of losing emerging-market benchmark eligibility has intensified concerns about future capital flows, trading liquidity and the financial accessibility of Southeast Asia’s largest economy.
A Historic Two-Day Market Decline
The scale of the October 19 selloff reflects the importance investors assign to Indonesia’s status within global equity benchmarks.
After declining 11.6% on Friday, Jakarta’s benchmark fell another 3.6% on Monday.
Calculated sequentially, the two declines represent a cumulative loss of approximately 14.8%, rather than the 15.2% obtained by simply adding the daily percentages.
Reuters reported that the two-session decline was more severe than any comparable selloff during the 1998 Asian financial crisis.
The index’s fall to a six-year low further illustrated the intensity of the market reaction.
The selling pressure followed MSCI’s proposal to move Indonesia directly from Emerging Market to Standalone Market status, bypassing the less severe Frontier Market classification.
That distinction was significant because standalone markets do not participate in the same broad emerging-market investment framework.
For investors whose mandates depend on benchmark eligibility, a potential change of this magnitude can affect portfolio construction well before the final classification decision takes effect.
The October 19 decline therefore reflected the market’s assessment of a future structural risk, rather than the implementation of an already completed downgrade.
MSCI Identifies Persistent Market-Accessibility Concerns
MSCI formally launched its consultation on October 15, citing concerns about the investability and functioning of Indonesia’s equity market.
The index provider identified persistent opacity in shareholding structures, suspected coordinated trading behavior and insufficient evidence that announced reforms had produced sustained improvements.
These concerns are directly relevant to institutional investors.
Transparent ownership information helps investors assess available free float, concentration risk and the capacity to establish or exit positions.
Reliable trading conditions are equally important because investors must be able to transact without excessive market impact or uncertainty about price formation.
MSCI acknowledged that Indonesian authorities had announced reforms, including enhanced shareholder disclosures, more detailed investor classifications and measures addressing highly concentrated share ownership.
However, the index provider concluded that market participants had not observed sufficiently consistent progress.
MSCI therefore proposed moving Indonesia to Standalone Market status rather than retaining its existing emerging-market classification.
The proposal remains subject to consultation.
MSCI will accept feedback from market participants through April 30, 2027, and has stated that its final decision will be announced on or before June 30, 2027.
The company also indicated that material improvements in market governance and functioning could warrant reconsideration.
Until a final decision is announced, Indonesia’s existing classification remains in place, subject to the index-related restrictions already established by MSCI.
Benchmark Eligibility Creates Capital-Flow Risk
The potential reclassification matters because international equity benchmarks influence how institutional capital is allocated.
Passive funds seek to replicate index composition, while active managers often use benchmarks to define their investment universes, measure performance and manage portfolio risk.
If Indonesian equities were removed from widely followed emerging-market indexes, certain investors could be required to reduce or eliminate positions.
Others might reassess exposure because a narrower investor base could affect market liquidity and the valuation of listed companies.
The scale of any resulting outflows would depend on the final decision, implementation arrangements and the mandates of affected investors.
These outflows have not yet occurred as a consequence of a completed reclassification.
Nevertheless, the possibility of future benchmark exclusions can influence prices immediately.
Investors anticipating lower demand may seek to reduce exposure before a formal index change.
When many participants attempt to adjust positions simultaneously, liquidity can deteriorate and price movements can become more pronounced.
The October 19 selloff illustrates how expected changes in market eligibility can affect asset prices before the underlying institutional decision is finalized.
Indonesia Introduces Emergency Trading Restrictions
Indonesian authorities responded to the market turmoil with measures intended to reduce volatility.
On October 19, the Indonesia Stock Exchange reduced its lower daily auto-rejection threshold for individual stocks from 15% to 7%.
The measure prevents sell orders below the permitted price limit from being accepted under the exchange’s trading rules.
The adjustment took effect on Monday and is scheduled to remain in place through December 31, 2026, subject to periodic reassessment.
The restriction is intended to give investors additional time to evaluate market information and reduce the speed of extreme individual-stock price declines.
However, trading limits do not eliminate the underlying concerns about market accessibility, ownership transparency or future index eligibility.
They can moderate the pace of price adjustment without necessarily changing investors’ assessment of fundamental or structural risk.
Exchange officials also engaged with MSCI to clarify the issues underlying the proposed reclassification.
For institutional investors, the distinction between short-term trading stabilization and sustained improvements in market governance is critical.
The longer-term outcome will depend on whether Indonesian authorities can demonstrate reforms that address the concerns identified by MSCI and its market participants.
Pressure Spreads Beyond the Equity Market
The reassessment of Indonesian financial assets was not confined to equities.
Reuters reported that selling pressure extended into the rupiah and Indonesian government bonds as investors reconsidered their exposure to the country.
This broader response matters because international portfolio allocations often involve multiple asset classes.
A deterioration in confidence toward a country’s equity market can influence currency positioning, risk limits and demand for other domestic securities.
The transmission is not automatic.
A potential equity-index downgrade is distinct from a sovereign credit-rating decision, and it does not by itself establish that government debt has become less creditworthy.
Nevertheless, concerns about market governance and capital access can affect the compensation investors require for holding local financial assets.
Currency weakness may also influence the returns earned by foreign investors after conversion into their home currencies.
These considerations can reinforce portfolio adjustments during periods of heightened uncertainty.
The October 19 market reaction therefore demonstrated how a classification proposal directed at equities can become relevant to broader international investment decisions.
A Market-Structure Shock, Not an Earnings Collapse
Indonesia’s selloff differs from a conventional equity correction driven primarily by disappointing corporate earnings.
The central development concerns the framework through which international investors gain exposure to the market.
That distinction is important for interpreting the magnitude of the decline.
Individual companies may continue generating revenue and operating cash flow even as their shares experience significant selling pressure.
Equity valuations can nevertheless fall if investors expect reduced liquidity, a smaller eligible buyer base or higher required returns.
In this case, the proposed MSCI reclassification introduced uncertainty about the future accessibility of Indonesian securities to benchmark-constrained institutional portfolios.
The resulting price adjustment should not be interpreted as evidence that the operating performance of Indonesian companies deteriorated by approximately 14.8% over two trading sessions.
Instead, it reflects a rapid reassessment of market-access risk and the financial consequences of a potential change in index eligibility.
For institutional investors, this distinction reinforces the importance of evaluating market structure alongside earnings, valuations and economic fundamentals.
Weekly Market Intelligence: Market Access Becomes a Financial Risk
Indonesia’s October 19 selloff illustrates how changes in expected benchmark eligibility can produce significant financial-market consequences.
The Jakarta benchmark’s 3.6% decline followed an 11.6% plunge on October 16, resulting in a compounded two-session loss of approximately 14.8%.
The scale of the decline reflects the importance investors assign to Indonesia’s continued participation in the emerging-market investment framework.
MSCI’s proposal remains under consultation, with a final decision expected no later than June 30, 2027.
The outcome will depend on whether Indonesian authorities can demonstrate sufficiently meaningful improvements in market governance, transparency and trading conditions.
Until then, investors face uncertainty over future index eligibility and the associated implications for foreign capital flows.
The immediate lesson extends beyond Indonesia.
Global benchmarks influence market access, portfolio mandates and the distribution of international investment capital. When confidence in a market’s eligibility deteriorates, asset prices can adjust sharply even before any formal reclassification occurs.
For institutional investors, the October 19 episode underscores the importance of assessing liquidity, ownership transparency and market governance as fundamental components of financial risk.
Indonesia’s historic selloff demonstrates that market accessibility is not merely a technical consideration. It can become a decisive factor in capital allocation and asset valuation.
Important Information
This material was prepared by Wavelength Financial Content, an independent third-party content provider, and is published with the authorization of Quassar Capital, L.P. ("Quassar Capital"). Opinions expressed are as of the date of publication and are subject to change without notice. They do not necessarily reflect the views of Quassar Capital or its affiliates.
This material is provided for informational purposes only. It is not investment, legal, or tax advice, a recommendation to take any action or make any investment decision, or an offer to sell or a solicitation of an offer to purchase any security, financial product, or interest in an investment vehicle. Forward-looking statements, forecasts, and estimates are illustrative, subject to risks and uncertainties, and may not be realized. Past performance is not indicative of future results.
Information has been obtained from sources believed to be reliable but has not been independently verified, and no representation or warranty is made as to its accuracy or completeness. References to third-party companies, products, or trademarks are for identification only and do not imply sponsorship, affiliation, or endorsement. See the Disclosures and Terms of Use pages on this website for additional information.
© 2026 Quassar Capital, L.P. All rights reserved. Reproduction or distribution of this material, in whole or in part, is prohibited without the prior written consent of Quassar Capital.