Oil Above $106 Exposes a Growing Divide Between U.S. Energy and Technology Stocks
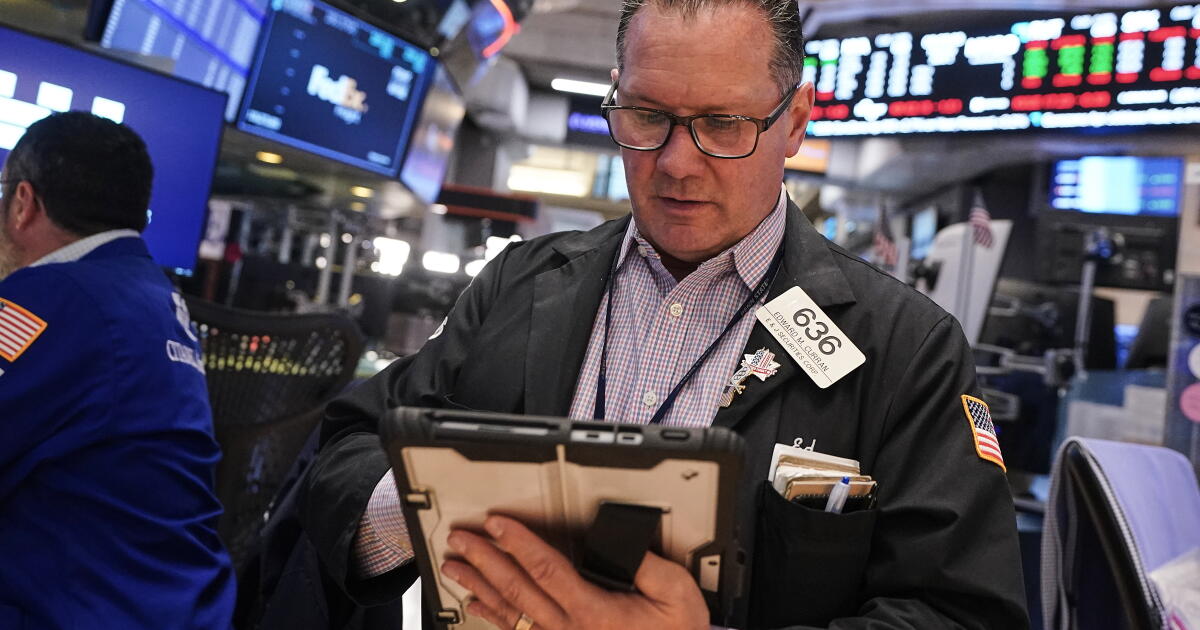
U.S. equity markets displayed a pronounced sector divergence on October 12, 2026, as rising crude oil prices supported energy producers while technology shares came under pressure.
Brent crude traded above $106 per barrel following attacks on Riyadh’s international airport over the weekend, renewing concerns about the security of energy infrastructure and regional supply flows. The international benchmark reached approximately $106.80 per barrel in intraday trading, an increase of roughly 2%.
The market response was uneven rather than uniformly negative.
At 11:28 a.m. Eastern Time, the Dow Jones Industrial Average had advanced 0.46% to 51,891.40, while the S&P 500 declined 0.05% to 7,807.50 and the Nasdaq Composite fell 0.33% to 27,275.77, according to Reuters.
Beneath those relatively modest index movements, the S&P 500 energy sector gained approximately 1.4%, while technology stocks declined 1.0%. The Philadelphia Semiconductor Index fell 2.7%.
The divergence illustrates a central feature of commodity-driven market shocks: the same increase in energy prices can strengthen earnings expectations for certain businesses while increasing costs and financial uncertainty for others.
For institutional investors, the significance lies not only in the direction of the major equity indexes, but in how changing commodity prices redistribute economic risk across sectors.
The Oil Market Reprices Supply Risk
The October 12 increase in crude prices reflected renewed geopolitical uncertainty surrounding energy infrastructure and international supply routes.
Reports of attacks involving Riyadh’s international airport heightened concerns about regional security. At the same time, a proposed cessation of attacks on energy facilities in the Russia-Ukraine conflict introduced a potentially offsetting development.
However, the scope and implementation of that proposed arrangement remained uncertain.
Brent crude’s advance to approximately $106.80 per barrel therefore reflected a market balancing renewed supply concerns against the possibility of reduced disruption elsewhere.
A geopolitical risk premium can increase oil prices even before a measurable reduction in production occurs. Market participants may demand higher prices to compensate for the possibility that future supply becomes less reliable or more expensive to transport.
That mechanism differs from a confirmed physical supply shortage.
The available evidence establishes that crude prices increased amid heightened geopolitical uncertainty. It does not establish the precise volume of production or exports that may ultimately be affected.
This distinction matters because the durability of an oil-price increase depends partly on whether the disruption remains a perceived risk or develops into a sustained constraint on physical supply.
Energy Producers Gain a Direct Earnings Advantage
Higher crude prices can provide an immediate financial benefit to companies with substantial upstream oil production.
For producers selling crude into international or domestic markets, higher realized prices generally increase revenue per barrel, assuming production volumes and contractual arrangements remain unchanged.
Because a portion of operating expenses is fixed or changes more slowly than commodity prices, an increase in realized selling prices can have a disproportionate effect on operating cash flow.
This relationship helps explain why energy equities advanced during Monday’s session.
Chevron shares gained approximately 1.4% in intraday trading, consistent with the broader improvement in energy-sector performance.
However, the benefits of higher oil prices are not uniform across the industry.
Integrated energy companies combine upstream production with refining, distribution and other operations. Their consolidated earnings depend on production volumes, realized commodity prices, refining margins, operating expenses and capital allocation.
Refiners may experience different financial outcomes depending on the relationship between crude input costs and the prices of gasoline, diesel and other refined products.
Consequently, the October 12 increase in energy shares should not be interpreted as evidence that every energy-related business will experience the same earnings improvement.
The more defensible conclusion is that higher crude prices strengthened the near-term earnings environment for upstream producers and contributed to a positive market response across the energy sector.
Technology Valuations Face a Different Set of Risks
Technology stocks moved in the opposite direction.
The S&P 500 technology sector declined approximately 1.0%, while the Philadelphia Semiconductor Index fell 2.7%, indicating that weakness was particularly pronounced among chipmakers.
The decline cannot be attributed exclusively to crude oil prices. Technology valuations also respond to company-specific developments, earnings expectations, competitive conditions and investor positioning.
Nevertheless, sustained energy inflation can affect technology companies through financial channels that differ from those facing oil producers.
The most important is the relationship between inflation expectations, interest rates and equity valuation.
When investors expect inflation to remain elevated, they may anticipate a more restrictive monetary policy environment or a longer period of relatively high interest rates.
Higher discount rates reduce the present value of future corporate cash flows, with the greatest sensitivity often occurring among businesses whose valuations depend heavily on earnings expected further into the future.
This relationship is especially relevant for growth-oriented technology companies.
The effect is not mechanical. A company’s valuation also depends on expected revenue growth, profitability, capital expenditure, competitive positioning and the risk premium investors require.
A technology company delivering stronger earnings growth can outperform even when interest rates remain elevated.
However, a sustained increase in energy prices introduces an additional source of uncertainty into the inflation and interest-rate assumptions used to value future earnings.
The October 12 divergence is therefore consistent with different sector sensitivities to commodity prices and financing conditions, without proving that oil alone caused the decline in technology shares.
The Broader Earnings Transmission Extends Beyond Energy
The financial effects of higher petroleum prices extend across the corporate economy.
Transportation companies, airlines, manufacturers and distribution businesses may face higher operating expenses when fuel and energy-intensive inputs become more expensive.
Whether those increases reduce profitability depends on the ability to pass costs through to customers, improve operating efficiency or offset higher expenses elsewhere.
Businesses with strong pricing power may preserve margins by increasing selling prices. Companies operating in highly competitive markets may have less flexibility.
Consumer-facing businesses face a related risk.
Higher gasoline and household energy costs can reduce the income available for discretionary purchases, potentially affecting demand for products and services unrelated to energy.
These transmission channels help explain why a commodity-price shock can alter relative earnings expectations even when the broad equity market shows limited movement.
They should not, however, be treated as confirmed financial results from the October 12 session.
The market data demonstrate a divergence between energy and technology shares. The ultimate effects on corporate revenue, margins and cash flow will depend on the persistence of higher energy prices and the ability of individual businesses to adjust.
Inflation Expectations Remain a Critical Variable
The oil-price increase occurred shortly before the scheduled release of U.S. consumer inflation data for September.
The Bureau of Labor Statistics is scheduled to publish the Consumer Price Index on October 14 at 8:30 a.m. Eastern Time.
That report will provide an official measure of price developments during September, rather than a direct assessment of the geopolitical events and oil-price movements observed on October 12.
The distinction is essential.
A rise in crude prices can eventually affect gasoline, transportation and production costs, but those effects do not necessarily appear immediately or proportionately in consumer inflation measures.
The transmission depends on refining margins, inventories, distribution costs, taxes, pricing decisions and the duration of the commodity-price change.
A temporary geopolitical premium may have limited consequences for underlying inflation if oil prices subsequently retreat.
A sustained increase, by contrast, can exert pressure on consumer purchasing power and corporate operating expenses while complicating the inflation outlook.
For equity valuations, the relevant issue is whether higher energy prices materially alter expectations for inflation and monetary policy.
The Federal Reserve’s decisions depend on a broader assessment of inflation, employment and economic activity. An isolated oil-price increase does not determine the appropriate policy response.
Nevertheless, the possibility of persistent energy-driven inflation can influence investors’ assumptions about future borrowing costs and the discount rates applied to equities.
Treasury-Market Closure Limits Cross-Asset Confirmation
The U.S. bond market was closed on October 12 in observance of the federal holiday, limiting contemporaneous price discovery in the Treasury cash market.
The Federal Reserve’s H.15 statistical release dated October 9 reported a 10-year Treasury constant-maturity yield of 5.22% for October 8, the latest observation in that release.
That figure provides a verified reference for prevailing interest-rate conditions, but it should not be interpreted as a live Treasury-market response to Monday’s oil-price increase.
This limitation is important because Treasury yields are a central input into equity valuation and broader financial conditions.
Changes in nominal yields, inflation compensation and real interest rates can help distinguish whether investors view an energy shock primarily as an inflationary development, a threat to economic growth or a temporary geopolitical event.
Without a contemporaneous cash Treasury-market response, Monday’s equity-sector movements offer clearer evidence of immediate market differentiation than of a definitive change in U.S. interest-rate expectations.
Implications for Institutional Portfolio Risk
The October 12 session demonstrates why broad equity indexes can provide an incomplete picture of changing market risk.
The S&P 500 was nearly unchanged at the referenced intraday observation, yet energy and technology shares experienced materially different movements.
For portfolios with concentrated sector exposures, those differences can be more consequential than the headline index return.
Energy producers offer direct sensitivity to commodity prices, while technology companies can be more exposed to changes in growth expectations, financing conditions and valuation multiples.
Other industries face different combinations of input-cost exposure, pricing power and demand sensitivity.
The resulting market environment is not adequately described as uniformly favorable or unfavorable for equities.
Instead, the rise in oil prices changes the relative economic assumptions supporting different business models.
The institutional implication is that portfolio risk should be assessed through earnings sensitivity, cash-flow durability, financing requirements and valuation exposure rather than through index-level performance alone.
The observed sector divergence does not establish a permanent change in market leadership.
Its persistence will depend on whether crude prices remain elevated, whether supply concerns translate into physical disruptions and whether higher energy costs begin to affect inflation expectations and corporate earnings forecasts.
A Sector Rotation With Broader Financial Significance
The October 12 increase in oil prices produced a clear intraday distinction within the U.S. equity market.
Brent crude traded near $106.80 per barrel, the energy sector advanced approximately 1.4%, and technology stocks declined approximately 1.0%, with semiconductor shares experiencing greater weakness.
The major indexes moved considerably less, illustrating how sector-level repricing can occur without a broad market correction.
The financial significance of the development rests on two different mechanisms.
Higher crude prices can strengthen upstream energy earnings and cash flow. At the same time, sustained energy inflation can pressure operating margins elsewhere and influence the interest-rate assumptions embedded in equity valuations.
Those effects are economically plausible but not yet fully observable in corporate financial results.
The central question is whether the increase in oil prices proves temporary or becomes a persistent feature of the operating and inflation environment.
For U.S. institutional investors, the October 12 divergence provides a timely illustration of how a single commodity shock can redistribute earnings opportunities and valuation risks across the equity market, even while headline indexes remain relatively stable.
Important Information
This material was prepared by Wavelength Financial Content, an independent third-party content provider, and is published with the authorization of Quassar Capital, L.P. ("Quassar Capital"). Opinions expressed are as of the date of publication and are subject to change without notice. They do not necessarily reflect the views of Quassar Capital or its affiliates.
This material is provided for informational purposes only. It is not investment, legal, or tax advice, a recommendation to take any action or make any investment decision, or an offer to sell or a solicitation of an offer to purchase any security, financial product, or interest in an investment vehicle. Forward-looking statements, forecasts, and estimates are illustrative, subject to risks and uncertainties, and may not be realized. Past performance is not indicative of future results.
Information has been obtained from sources believed to be reliable but has not been independently verified, and no representation or warranty is made as to its accuracy or completeness. References to third-party companies, products, or trademarks are for identification only and do not imply sponsorship, affiliation, or endorsement. See the Disclosures and Terms of Use pages on this website for additional information.
© 2026 Quassar Capital, L.P. All rights reserved. Reproduction or distribution of this material, in whole or in part, is prohibited without the prior written consent of Quassar Capital.